Rental and chauffeured transport in Qatar is a volume business with thin margins per car and a serious licensing regime. Here is the licensing path, how fleets are financed and the per-vehicle numbers that decide whether it works.
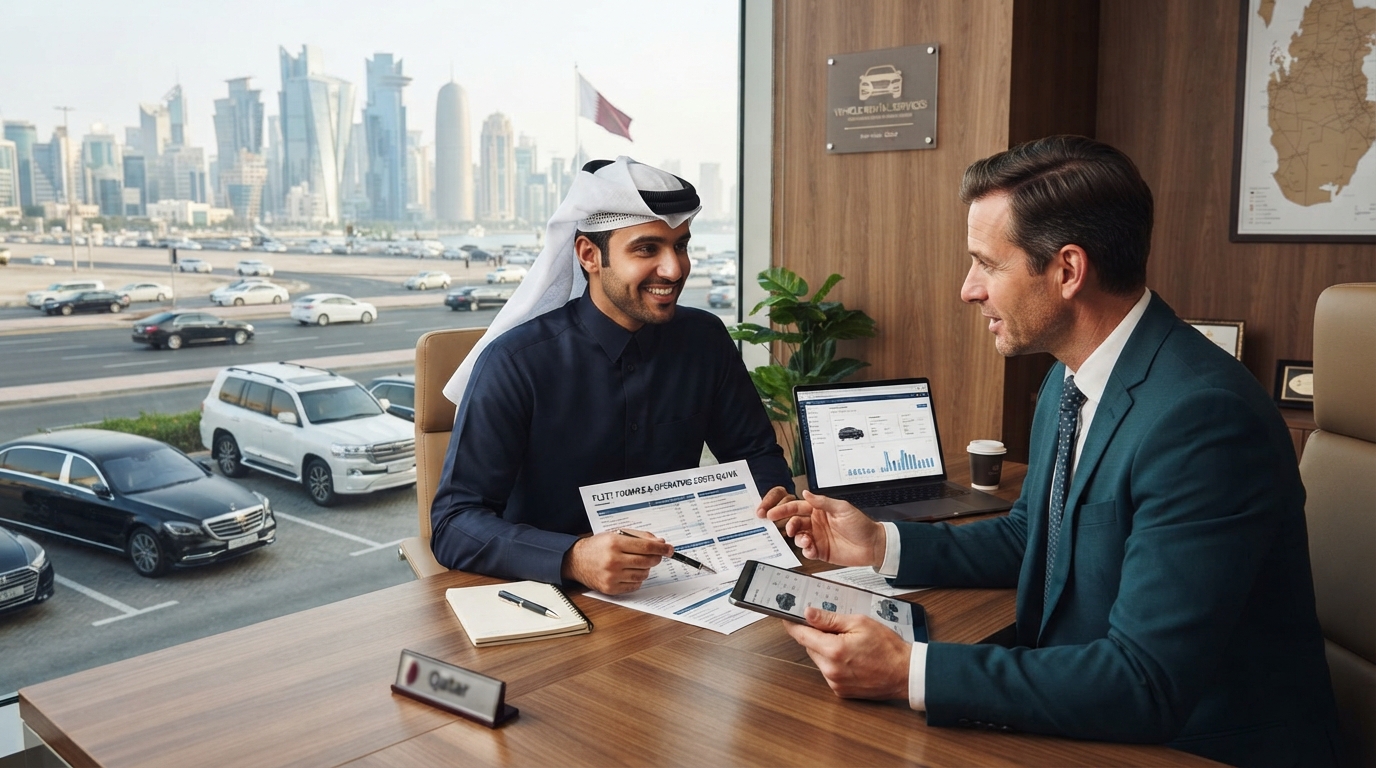
Every large event, every new hotel and every corporate arrival in Qatar creates demand for cars with drivers and cars without. It is a market with real growth and very little room for error: the assets depreciate daily, the regulator is strict, and a fleet of thirty cars financed at the wrong rate can lose money at 80 per cent utilisation. The operators who succeed run it as a numbers business from the first vehicle.
Licensing: two different businesses
- Self-drive car rental is licensed as a commercial activity through the Ministry of Commerce and Industry, with vehicles registered as rental vehicles at the Traffic Department, comprehensive insurance for rental use, and a physical office and parking yard. Rental cars carry distinct registration and the customer's licence and identity are verified for every hire.
- Chauffeured limousine and passenger transport is regulated under the Ministry of Transport's passenger-transport framework; operators need a transport licence, vehicles that meet age and specification rules, drivers with the correct licence category and permits, and the company must be approved to operate. Airport and hotel access are separately arranged. The bar is higher and the process longer; plan several months.
Both require capital, a lease, visas for drivers and staff, and insurance premiums that are materially higher than private cover. Ride-hailing platforms operate through licensed limousine companies, which is how many new operators enter: with a fleet contracted to a platform.
Financing the fleet
Few operators buy fleets with cash. The options:
1. Bank vehicle finance: 3 to 5 year terms, 20 to 30 per cent down, rates tracking the central bank rate plus a margin; the bank holds the registration until settled.
2. Dealer finance and fleet programmes: manufacturers' finance arms offer fleet rates and buy-back guarantees on volume, which fix your residual-value risk.
3. Operating lease from a leasing company: the operator rents the cars it rents out; thin margins but no capital and no residual risk; workable for chauffeured contracts with a fixed monthly revenue.
A 30-car starting fleet of mid-size sedans at QAR 90,000 to 110,000 each needs QAR 700,000 to 1 million of equity and QAR 2 to 2.5 million of finance, plus QAR 400,000 to 600,000 for setup, yard, systems and working capital.
Unit economics per car
Take a mid-size sedan on the self-drive side: - Revenue: daily rates of QAR 120 to 180 for walk-in hire, but most fleet revenue comes from monthly corporate hires at QAR 2,200 to 3,200 a month. At 75 per cent utilisation, that is QAR 1,650 to 2,400 realised a month.
- Costs: finance QAR 1,600 to 2,000; insurance QAR 300 to 450; maintenance and tyres QAR 300; registration, tracking, cleaning and admin QAR 150 to 250. Total QAR 2,350 to 3,000 a month.
The arithmetic shows why utilisation and residual value decide everything. Below 70 per cent utilisation a financed sedan loses money; above 85 per cent with a dealer buy-back it makes a modest, reliable margin. Chauffeured vehicles run on a different model: driver salary, accommodation and visas (QAR 3,500 to 5,000 a month all-in) added to the car, against corporate and hotel contracts at QAR 8,000 to 15,000 a month per car with driver, or platform trips. Margins are better per vehicle; the licensing and staffing burden is higher.
The operating discipline that protects margin
1. Telematics on every car: location, speed and mileage. It reduces accidents, catches misuse and settles disputes.
2. Damage process: photographs at every handover and return, a published damage tariff, and deposits taken by card pre-authorisation.
3. Traffic fines: a daily check and re-billing within the week. Unbilled fines are the silent margin killer in Qatar.
4. Fleet age: rotate cars at 24 to 36 months or 80,000 to 100,000 km; older cars cost more in downtime than they save in finance.
5. Corporate contracts with 12-month terms, a replacement-vehicle clause and payment terms of 30 days, not 90.
6. Peak planning: events, winter season and Ramadan patterns are predictable; add short-term capacity through partners rather than buying cars for peaks.
Who makes money in this market
Operators with corporate and hotel contracts covering 60 per cent of the fleet, a dealer relationship that fixes residuals, and a back office that bills fines and damage within days. The walk-in customer at the airport is the marketing; the contracts are the business.