Qatar's banks lend, the development bank guarantees and investors are looking; yet most SMEs are still financing growth from the owner's pocket. Here is what each source wants to see and how to prepare for it.
Ask an owner of a five-year-old contracting or trading company in Doha how they fund a large new order and the honest answer is usually: supplier credit, a personal loan, and prayer. That is not because finance is unavailable. Qatar's banks run active SME desks, the development bank guarantees a large share of the risk on qualifying loans, and there is more private equity looking at the country than most owners realise. The gap is preparation. Finance goes to companies that look financeable on paper.
The sources and what they are for
1. Working-capital facilities from banks: overdrafts, invoice or contract financing, letters of credit and guarantees for trade. Sized against confirmed contracts and receivables; priced at the central bank rate plus 3 to 6 per cent for SMEs; secured on receivables, the owner's personal guarantee and often property.
2. Project and asset finance: term loans for equipment, vehicles, fit-out or a factory, 3 to 7 years, secured on the asset plus guarantees.
3. Development-bank programmes: Qatar Development Bank's guarantee scheme covers a substantial portion of a qualifying SME loan from a partner bank, which is what makes the bank say yes; direct lending, export financing and support for manufacturing, agriculture, tourism and technology; and advisory and incubation programmes. Eligibility typically favours Qatari-owned or majority-Qatari companies, so check before building the plan around it.
4. Bank guarantees and bonds: performance, advance-payment and tender bonds that every contractor needs; they consume facility limits and need cash margin, so plan the bond line with the working-capital line.
5. Equity and private investors: family offices, local angel groups and regional funds; they buy a share, not a loan, and want a shareholders' agreement, audited accounts and a plan for exit or dividends.
6. Supplier and customer finance: extended supplier terms, customer advances against bank guarantees, and equipment vendors' finance arms. Cheap when it is available and under-used.
What a bank wants to see
- Audited financial statements for two to three years, and current management accounts. Unaudited numbers on a spreadsheet stop the conversation.
- A commercial registration, tax card and clean tax filing history with the General Tax Authority.
- Contracts and receivables: signed contracts, work orders and an aged receivables list; the bank lends against these more than against the story.
- Bank statements showing revenue actually passing through the business account; cash businesses that bank nothing cannot be financed.
- The owner: personal guarantee, personal credit record and, for larger facilities, personal assets.
- A purpose and a repayment source: "working capital for the QAR 4 million contract with X, repaid from its milestone payments" is bankable; "expansion" is not.
What an investor wants to see
A business that can run without the founder for a month; a market position that can be explained in two sentences; audited accounts and a cap table with no side deals; a use of funds with milestones; and an honest valuation. Regional investors value profitable SMEs in Qatar at roughly 4 to 8 times sustainable annual earnings depending on sector and growth; technology companies are valued differently and mostly on revenue growth. Expect a shareholders' agreement with board rights, information rights and protections against the founder selling or diluting without consent.
Preparing the file
1. Get audited by a firm on the approved list, this year, even if no one has asked.
2. Run every riyal through the business bank account for twelve months.
3. Build a simple three-year forecast: revenue by contract or product line, gross margin, overheads, cash flow month by month, and the facility drawn and repaid within it.
4. Clean up the corporate structure: shareholders, authorised signatories, and any unregistered arrangements with partners.
5. Approach two banks and the development bank at the same time, with the same file, and let them compete on pricing and security.
Where a finance adviser earns the fee
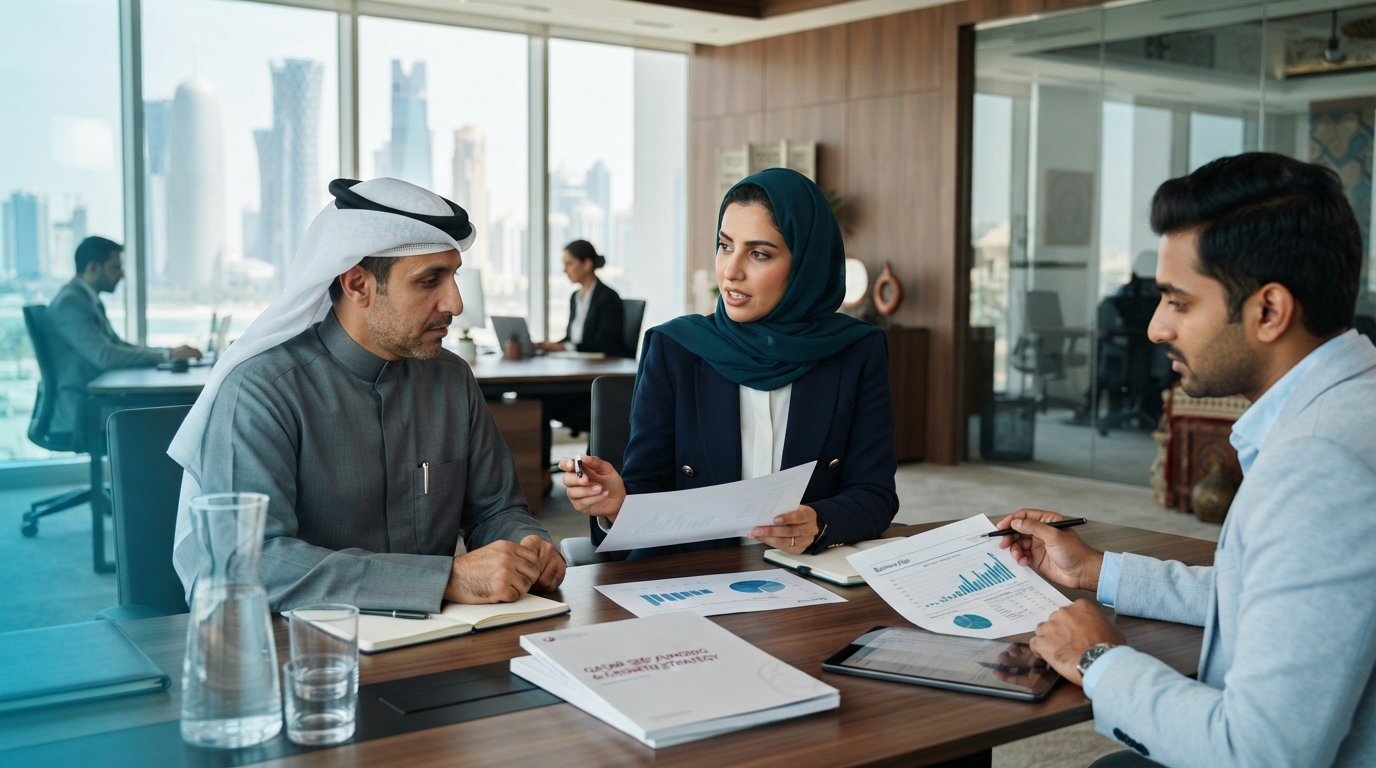
A good corporate-finance adviser or accountant in Doha will structure the request so the facility fits the cash cycle (bond line, working capital and term loan sized together), prepare the bank pack in the format each bank uses, present the file, and negotiate pricing and security. Fees run from QAR 15,000 for a bank pack to 1 to 2 per cent of the facility for a fully negotiated financing. On a QAR 5 million facility, a half-percent improvement in the rate and one less asset pledged pays for that several times.
This article is general information for readers in Qatar and is not legal, tax or financial advice. Rules and fees change; confirm the current position with a licensed professional.